
7 Financial Rules You Should Know by 30
Categories
- Tips
- Guides
- Market Insights
- Articles
Recent Posts
Tips / 28 Sept 2026
How to Check Whether a Plot of Land Is Legally Safe to Buy
Guides / 28 Sept 2026
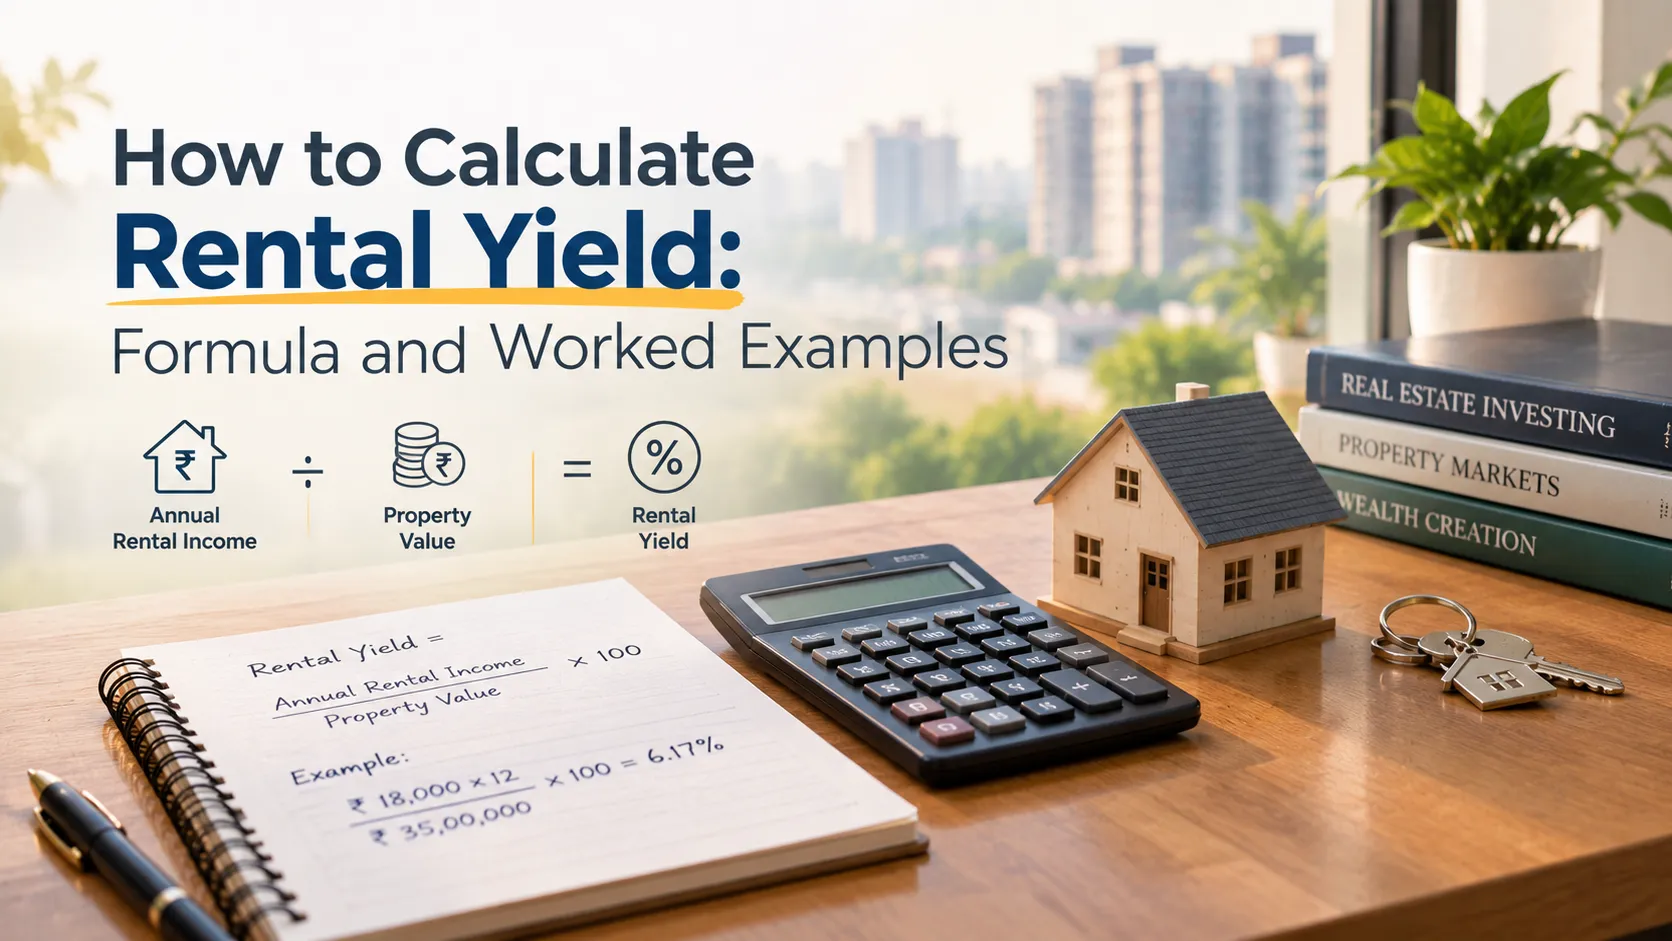
How to Calculate Rental Yield: Formula and Worked Examples
Guides / 26 Sept 2026
How Much Home Loan Can You Get on Your Salary in 2026?
Guides / 25 Sept 2026
10 Things to Check in a Property Sale Deed Before Registration
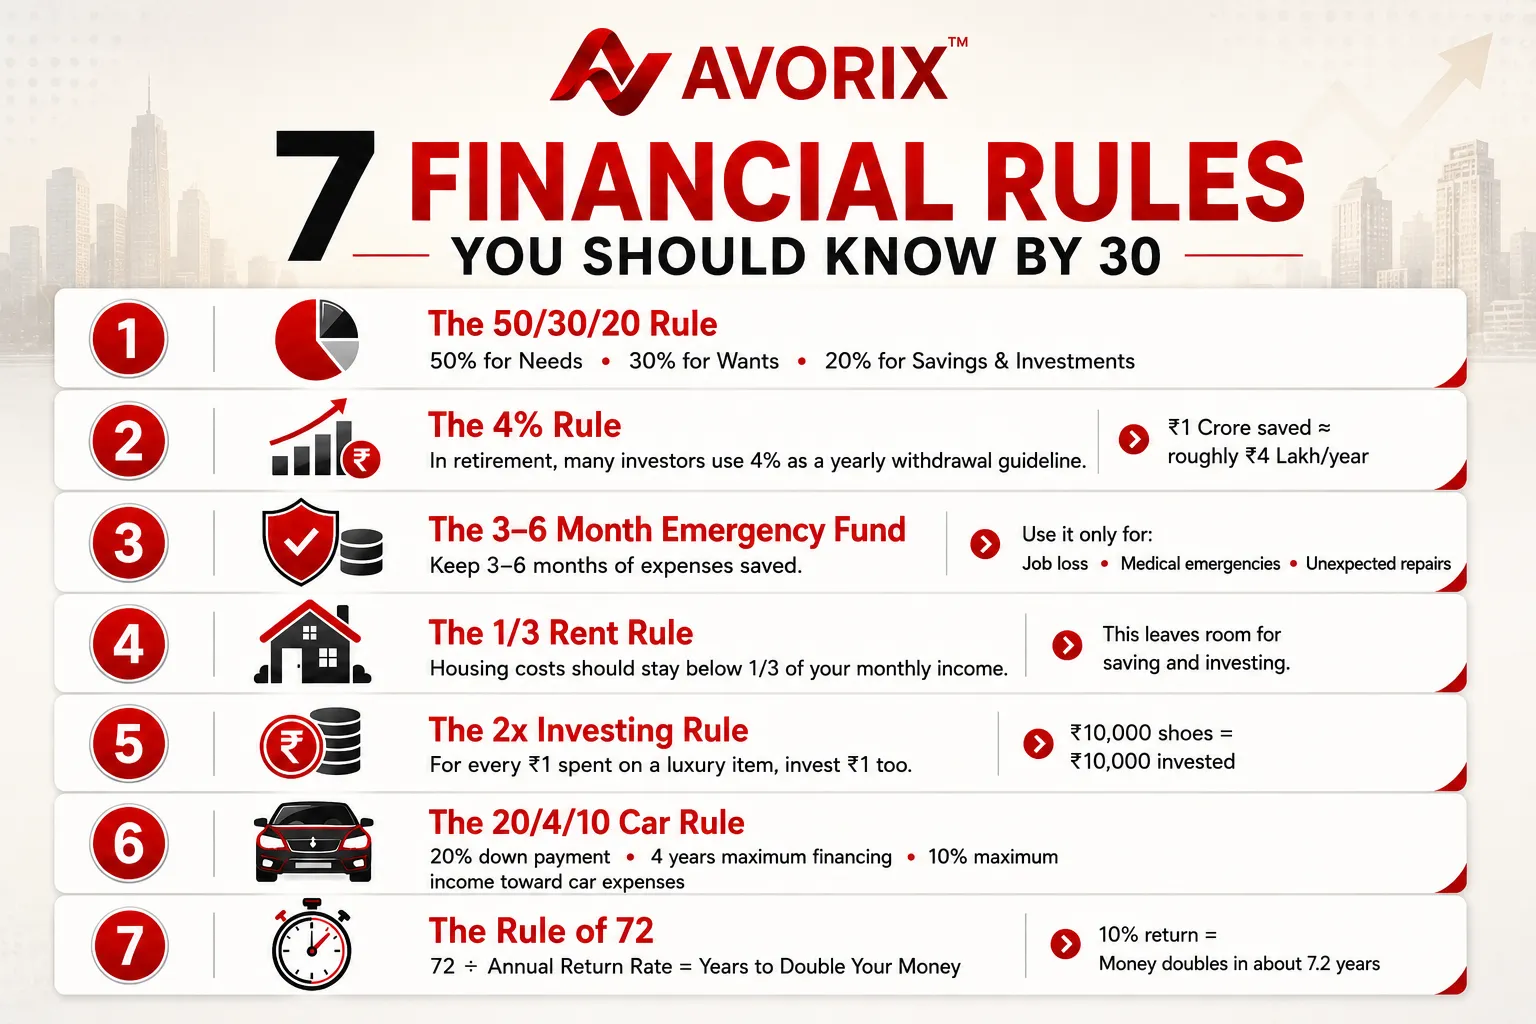
These 7 financial rules will change how you think about money, investing, and spending before 30. Simple, practical, and built for the Indian context in 2026.
Most of us reach our late twenties having learned how to earn money but not how to manage it. School didn't cover it. College mostly didn't either. And by the time you're earning a real salary, you're making financial decisions — about rent, about spending, about loans — based on guesswork, peer pressure, or whatever felt right at the time.
The frustrating thing is that good financial decision-making isn't complicated. It comes down to a handful of principles that, once understood, make most money decisions significantly clearer. Not perfect. Just clearer.
Here are seven rules that financially stable people tend to know and follow — and that most people in their twenties have never formally heard of.
Table of Contents
- 1. The 50/30/20 Rule — The Foundation of Every Budget
- 2. The 4% Rule — How to Think About Retirement Wealth
- 3. The 3 to 6 Month Emergency Fund — Before Anything Else
- 4. The 1/3 Rent Rule — The Number Your Landlord Hopes You Don't Know
- 5. The 2x Investing Rule — Every Luxury Has a Price
- 6. The 20/4/10 Car Rule — Before You Sign the Loan
- 7. The Rule of 72 — Understanding How Compounding Actually Works
- A Real-World Observation: Why These Rules Work Together
- Common Mistake: Investing Before Stabilising the Foundation
- What This Has to Do With Property
1. The 50/30/20 Rule — The Foundation of Every Budget
If you're only going to learn one budgeting framework, make it this one.
Divide your monthly take-home income into three buckets:
50% for Needs — rent, groceries, utilities, EMIs, transport. The non-negotiables.
30% for Wants — dining out, subscriptions, travel, entertainment. Things you choose to spend on.
20% for Savings and Investments — this comes out first, not last. The moment you start treating savings as what's left over after everything else, you'll consistently save very little.
The reason this rule matters so much isn't the specific percentages — your situation might require adjustments. It's the mental model it creates. Most people in their twenties have no conscious structure to their spending. Money comes in, money goes out, and the month ends with whatever's left. The 50/30/20 rule replaces that randomness with intentionality.
One honest note: in high-rent cities like Mumbai, Gurugram, or South Delhi, housing alone can consume 40% to 50% of income. If that's your situation, the 30% wants bucket needs to compress — not the 20% savings bucket.
2. The 4% Rule — How to Think About Retirement Wealth
This rule sounds like it's only for people nearing retirement. It's not. It's one of the most clarifying frameworks for understanding how much wealth you actually need — and therefore how much you should be building toward.
The 4% rule — originally derived from William Bengen's research in 1994 on sustainable retirement withdrawals — suggests that if you withdraw 4% of your total invested corpus each year, your money is likely to last through a 30-year retirement.
In Indian terms: ₹1 crore saved = roughly ₹4 lakh per year in sustainable withdrawals.
That number is both clarifying and sobering. If you want ₹12 lakh per year in retirement income, you need ₹3 crore invested. If you want ₹24 lakh per year, you need ₹6 crore. Suddenly the gap between "I'm saving something" and "I'm saving enough" becomes very visible.
The earlier you understand this rule, the more time you have to close that gap without requiring heroic savings rates in your forties.
3. The 3 to 6 Month Emergency Fund — Before Anything Else
This isn't technically an investing rule. It's a survival rule. And it should come before any investment conversation.
An emergency fund of 3 to 6 months of living expenses — kept in a liquid savings account or a short-term liquid mutual fund — acts as a financial buffer for:
- Job loss or unexpected income disruption
- Medical emergencies not covered by insurance
- Urgent home or vehicle repairs
The most common mistake people make with this: they invest before they have an emergency fund. Then an unexpected expense hits, they withdraw from their investments at the wrong moment — often at a market low — and pay penalties, taxes, and lose compounding time in the process.
Build the emergency fund first. Invest after. In that order.
4. The 1/3 Rent Rule — The Number Your Landlord Hopes You Don't Know
Housing costs — rent, in most cases — should not exceed one-third of your monthly take-home income.
Why? Because rent is a fixed, recurring, non-negotiable cost. If it consumes too much of your income, it leaves too little room for savings, investments, EMI flexibility, or any financial breathing space. When an unexpected cost hits, there's nowhere to pull from.
In practice, this rule is under pressure in major Indian cities. A ₹40,000 monthly rent in Noida or Delhi NCR is not unusual for a decent 2 BHK. For someone earning ₹80,000 take-home, that's exactly 50% of income on rent — well above the 1/3 benchmark.
The rule doesn't mean you should always spend less on housing than feels right. It means you should make the trade-off consciously. If you're paying 50% of income in rent, you need to know that means your savings rate is being compressed — and plan accordingly.
This is exactly why many people in their late twenties start seriously evaluating property ownership. At a certain point, an EMI on a property you own starts making more financial sense than rent that builds no equity. The maths isn't always in favour of buying — but the 1/3 rent rule is often the trigger that starts the calculation.
5. The 2x Investing Rule — Every Luxury Has a Price
This one is less well-known but practically powerful.
The 2x rule: for every rupee you spend on a luxury item, invest an equal amount.
- ₹10,000 shoes? ₹10,000 invested.
- ₹50,000 watch? ₹50,000 invested.
- ₹1,50,000 holiday? ₹1,50,000 invested.
The rule doesn't tell you not to buy the luxury item. It tells you that the true cost of the luxury is double — and if you can't afford both the item and the investment, you can't actually afford the item.
What this does psychologically is interesting. It makes you genuinely weigh discretionary spending against investment opportunity. It removes the illusion that treating yourself is financially neutral. And for people who tend to justify individual purchases as "just this once," it creates an automatic accountability mechanism.
Practically, you don't have to invest in exactly the same amount every time. But the habit of pairing discretionary spending with investment action — even at a smaller ratio — is one of the behaviours that distinguishes people who build wealth in their thirties from those who don't.
6. The 20/4/10 Car Rule — Before You Sign the Loan
Cars are one of the largest financial decisions most people make in their late twenties. They're also one of the most emotionally driven — and therefore one of the areas where bad financial decisions cluster.
The 20/4/10 rule gives you a simple framework:
20% — put at least 20% as a down payment.
4 years maximum — don't finance a car for longer than 4 years.
10% maximum — total car-related expenses (EMI, fuel, insurance, maintenance) should not exceed 10% of your gross monthly income.
Why does this matter? A car is a depreciating asset. It loses value continuously from the day you drive it out of the showroom. Taking a 7-year loan on a car to reduce the monthly EMI to something "manageable" means you're paying interest on something that's simultaneously declining in value — and you may owe more than the car is worth for several years.
The 10% rule is the most commonly violated. Someone earning ₹1 lakh per month taking an EMI of ₹20,000 on a car — plus insurance, fuel, and maintenance — is putting 25% or more of income into a depreciating asset. That's money not building equity, not compounding, not working.
7. The Rule of 72 — Understanding How Compounding Actually Works
This is one of the most useful mental shortcuts in personal finance.
Divide 72 by your expected annual return rate. The result is approximately how many years it takes to double your money.
- 6% return → 72 ÷ 6 = 12 years to double
- 10% return → 72 ÷ 10 = 7.2 years to double
- 12% return → 72 ÷ 12 = 6 years to double
Why this matters: it makes the value of both return rate and time viscerally clear. A 2% difference in annual return doesn't sound significant. The Rule of 72 shows you it's the difference between doubling your money in 12 years versus 6 years — a 6-year gap that compounds further into enormous differences over a lifetime.
It also explains why starting to invest at 25 versus 35 is so consequential. Ten extra years of compounding at 10% doesn't just add 10% more money — it means your money has had one more full doubling cycle. On ₹10 lakhs invested at 25 versus 35 with a 10% return to age 60, the difference in final corpus is staggering.
The rule isn't precise — it's a mental model, not a financial calculator. But it's one of the most useful ways to intuitively understand why time in the market is the single most powerful variable in wealth building.
A Real-World Observation: Why These Rules Work Together
These seven rules aren't independent. They're a system.
The 50/30/20 rule creates the budget. The emergency fund protects the budget from collapse. The 1/3 rent rule keeps the biggest fixed cost in check. The 2x investing rule disciplines discretionary spending. The 20/4/10 rule prevents cars from eating investment capacity. The Rule of 72 shows you why all of this matters over time. And the 4% rule tells you what you're building toward.
A 28-year-old who genuinely internalises all seven of these will make consistently better financial decisions than someone who simply earns more but has no framework guiding their choices.
Common Mistake: Investing Before Stabilising the Foundation
The most frequent financial error people make in their late twenties is jumping straight into investing without first stabilising the three foundations: a working budget, an emergency fund, and controlled fixed costs.
Investing ₹5,000 per month in equity funds while carrying high-interest personal loan debt at 18% interest is arithmetically backwards — the loan interest is eating more than the investment can reasonably grow. Stabilise first. Then invest.
What This Has to Do With Property
Here's the Avorix perspective: these rules change the property decision meaningfully.
The 1/3 rent rule often creates the tipping point. The 50/30/20 rule shows you how much you can put toward an EMI. The Rule of 72 demonstrates why buying earlier — even imperfectly — can be smarter than waiting for perfect conditions. And understanding the 4% rule reframes property ownership as part of a broader wealth-building picture rather than just a lifestyle choice.
When these rules are applied to a real Delhi NCR or Noida property decision, the maths tends to shift — sometimes significantly — toward buying being more sensible than indefinite renting. Not always. But more often than most people realise before they run the numbers.
Thinking about how property fits into your financial picture in Delhi NCR? Speak with a local expert who can help you run the real numbers — not just the headline EMI — so the decision is grounded in actual financial logic rather than gut feel. #PropertyKaDNA
Tags
Tags
Frequently Asked Questions
About the Author
Admin
Top 5 Best Properties in Delhi NCR This Week
Handpicked properties with best price & location
Popular in Greater Noida
Top-rated residential & commercial projects across Greater Noida