
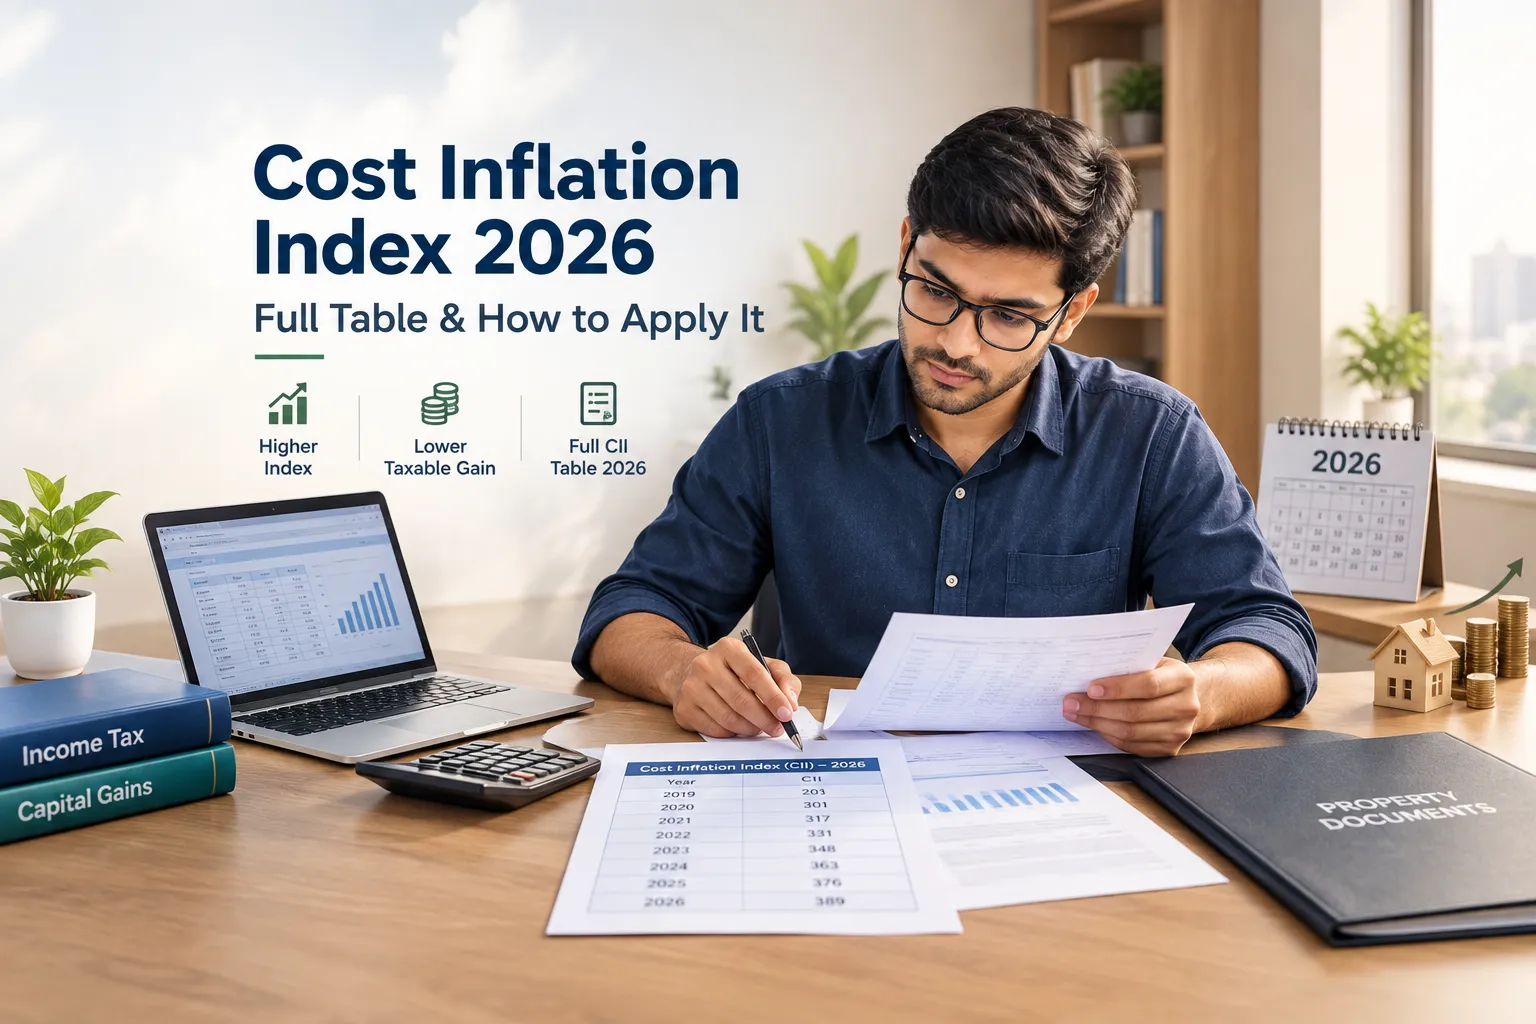
Cost Inflation Index 2026: Full Table and How to Apply It
Categories
- Tips
- Guides
- Market Insights
- Articles
Recent Posts
Tips / 28 Sept 2026
How to Check Whether a Plot of Land Is Legally Safe to Buy
Guides / 28 Sept 2026
How to Calculate Rental Yield: Formula and Worked Examples
Guides / 26 Sept 2026
How Much Home Loan Can You Get on Your Salary in 2026?
Guides / 25 Sept 2026
10 Things to Check in a Property Sale Deed Before Registration
CII for FY 2026-27 is notified at 384, but whether that number actually helps you comes down to one date: 23 July 2024. Here's the full table from 2001-02 onward, the indexation cutoff rule most explainers skip, and a worked example of the calculation.
Cost Inflation Index 2026 is set at 384, notified by CBDT for FY 2026-27. Cost Inflation Index numbers like this one get quoted constantly around tax season, and most explanations stop at "here's the table, plug in the numbers." CII 2026 deserves a more honest starting point: whether this figure does anything for your tax bill at all depends entirely on one date, not on the number itself. Cost Inflation Index Table lookups are only useful once you know whether you actually qualify to use indexation in the first place, and since July 2024, a large share of property sellers don't.
Here's the full table, the one date that decides whether any of it applies to you, and the actual calculation once it does.
What the Cost Inflation Index Actually Does
Think of CII as a currency converter for time. ₹25 lakh in 2010 doesn't buy what ₹25 lakh buys today, and taxing someone on the full difference between their old purchase price and today's sale price would tax them partly on inflation, not on real gain. CII converts your old purchase price into "today's rupees" before the tax department calculates what you actually profited, so you're taxed on genuine appreciation, not on the fact that money was worth more a decade ago.
Cost Inflation Index Table: FY 2001-02 to FY 2026-27
| Financial Year | CII |
|---|---|
| 2001-02 | 100 |
| 2002-03 | 105 |
| 2003-04 | 109 |
| 2004-05 | 113 |
| 2005-06 | 117 |
| 2006-07 | 122 |
| 2007-08 | 129 |
| 2008-09 | 137 |
| 2009-10 | 148 |
| 2010-11 | 167 |
| 2011-12 | 184 |
| 2012-13 | 200 |
| 2013-14 | 220 |
| 2014-15 | 240 |
| 2015-16 | 254 |
| 2016-17 | 264 |
| 2017-18 | 272 |
| 2018-19 | 280 |
| 2019-20 | 289 |
| 2020-21 | 301 |
| 2021-22 | 317 |
| 2022-23 | 331 |
| 2023-24 | 348 |
| 2024-25 | 363 |
| 2025-26 | 376 |
| 2026-27 | 384 |
2001-02 (index 100) is the base year for all calculations. If you acquired a property before 1 April 2001, you're allowed to use its fair market value as on that date as the cost of acquisition, rather than the original purchase price, whichever works out more favourably for you.
The Date That Decides Whether Any of This Applies to You
This is the part most CII explainers skip, and it's the single most important thing in this entire article. Budget 2024 changed how long-term capital gains on land and buildings are taxed, and the cutoff is 23 July 2024.
Property acquired before 23 July 2024: You (if an individual or HUF) can choose between paying 12.5% LTCG tax without indexation, or 20% with indexation, whichever results in lower tax. CII still matters for you.
Property acquired on or after 23 July 2024: LTCG is taxed flat at 12.5%, with no indexation option at all. CII plays no role in your capital gains calculation.
In other words, if you bought your flat, plot, or house after that date, you can stop reading the rest of this table with any expectation it'll lower your tax bill, it won't, because indexation simply isn't available to you anymore. If you bought before that date, the rest of this is genuinely useful, and worth calculating both ways before you file.
How to Calculate Indexed Cost of Acquisition
For those who do have the indexation option, the formula is straightforward:
Indexed Cost of Acquisition = Original Cost of Acquisition × (CII of Year of Sale ÷ CII of Year of Purchase)
Worked example: Say you bought a flat in FY 2010-11 for ₹25,00,000, and you're selling it in FY 2026-27.
Indexed Cost = ₹25,00,000 × (384 ÷ 167) = ₹25,00,000 × 2.2994 = approximately ₹57,48,503
That ₹57.48 lakh, not your original ₹25 lakh, is what gets subtracted from your sale price to arrive at your taxable long-term capital gain, if you choose the 20%-with-indexation option. Compare that resulting tax figure against the flat 12.5%-without-indexation alternative, and file whichever comes out lower.
Indexed Cost of Improvement Works the Same Way
Any capital improvement you made to the property, a major renovation, an extension, not routine repairs, can also be indexed, using the CII of the year the improvement was actually carried out, not the year you bought the property. The formula mirrors the acquisition cost calculation, just applied to the improvement expense and its own purchase-year CII.
The Mistake People Actually Make With CII
It's rarely a calculation error. It's applying indexation to a transaction that no longer qualifies for it, either because the property was bought after 23 July 2024, or because the asset class itself, listed shares and equity mutual funds, for instance, was already excluded from indexation benefits well before this. Before you touch the CII table at all, confirm two things: what you're selling, and when you acquired it. The table is only step two.
The Bottom Line
CII for FY 2026-27 is 384, up from 376 the year before, a fact that will matter enormously to some sellers and not at all to others, depending entirely on when they bought. If you're planning a property sale this year, the number worth writing down first isn't 384, it's your own acquisition date against 23 July 2024. Everything else follows from that.
Tags
Tags
Frequently Asked Questions
About the Author
Admin
Top 5 Best Properties in Delhi NCR This Week
Handpicked properties with best price & location
Popular in Greater Noida
Top-rated residential & commercial projects across Greater Noida