
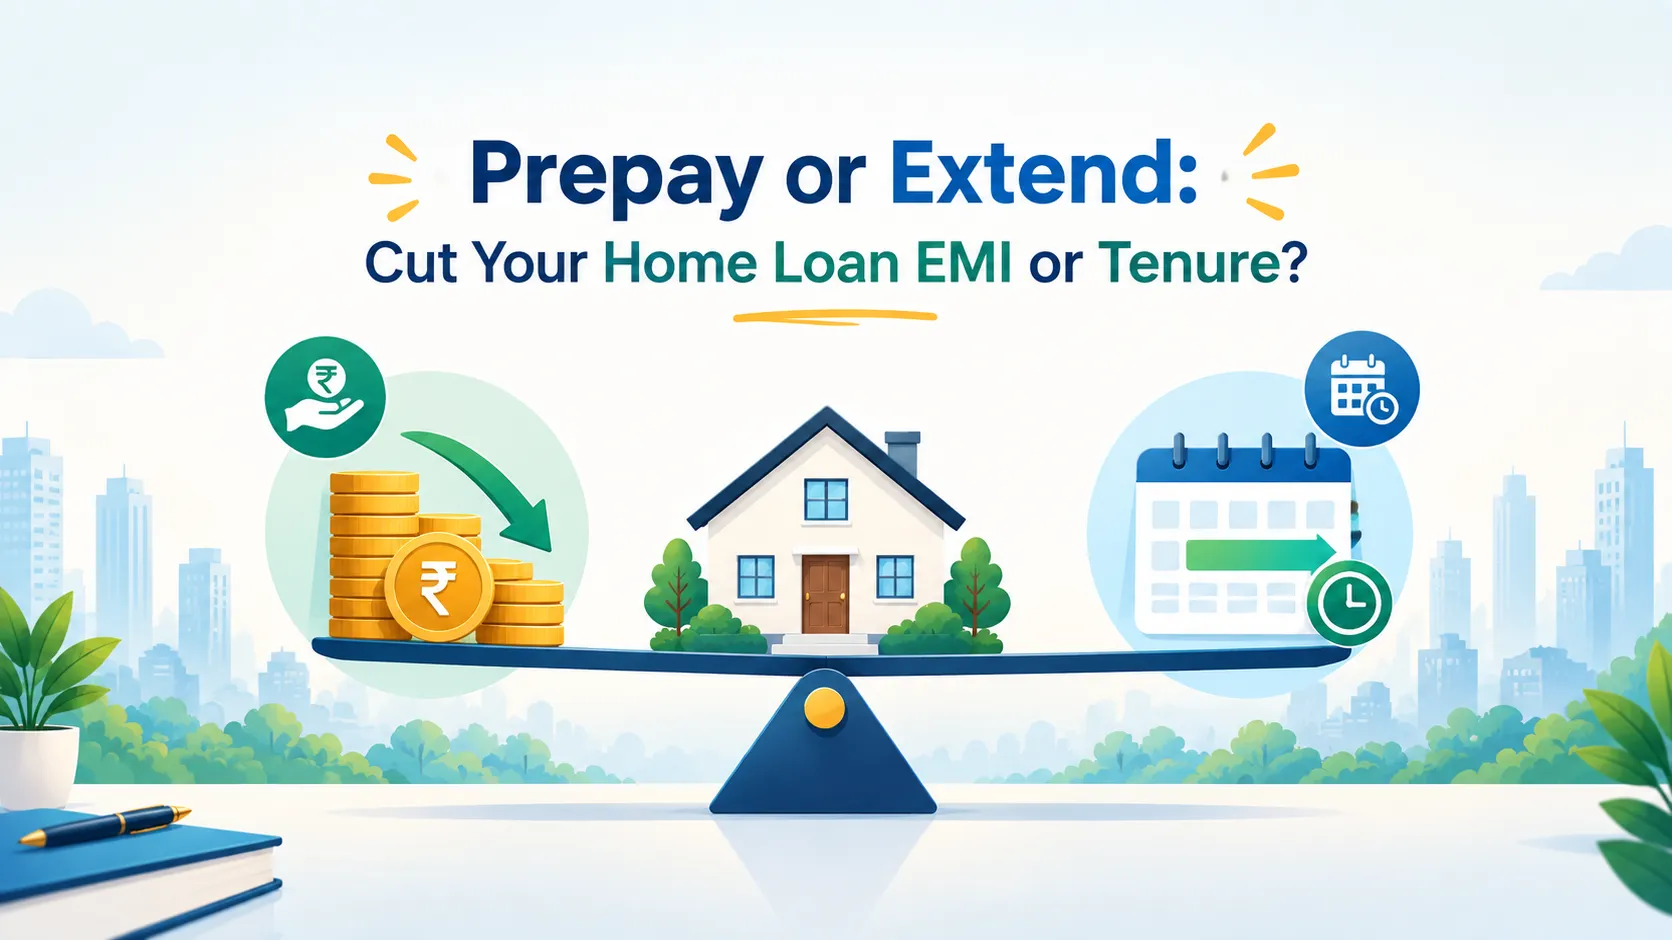
Prepay or Extend: Cut Your Home Loan EMI or Tenure?
Prepay or Extend: Cut Your Home Loan EMI or Tenure?
Categories
- Articles
- Guides
- Market Insights
Recent Posts
Articles / 16 Sept 2026
What Counts as a Good Rental Yield in India?
Guides / 16 Sept 2026
Home Loan Interest Rates 2026: Compare 15 Major Banks
Market Insights / 16 Sept 2026
Ganesh Chaturthi Property Deals: Payment Plans Over Freebies
Market Insights / 14 Sept 2026
Property Tax in Noida: How to Calculate and Pay It
Every home loan prepayment comes with the same quiet decision: reduce your EMI or reduce your tenure? Most borrowers pick whichever sounds nicer that month. Here's the actual math behind both options, when each one is genuinely the smarter call, and what the RBI's 2026 prepayment rules mean for you.
Home Loan Prepayment forces a decision most borrowers don't realise they're making until the bank asks: Reduce EMI or Tenure? It sounds like a small administrative choice, a checkbox on a form. It isn't. The same lump sum, applied to your Home Loan Tenure instead of your Home Loan EMI, can save you lakhs more over the life of the loan, or cost you that flexibility, depending on what you actually need. Most people pick the option that feels nicer that month and never revisit the math.
Here's what most advice on this skips: it tells you tenure reduction "saves more interest," states the obvious, and moves on. It doesn't tell you when the lower-EMI option is genuinely the smarter call, or how to decide which one your specific situation calls for. This one does both.
Table of Contents
- The Choice That Looks Small But Isn't
- How Home Loan Prepayment Actually Works
- The Numbers: Same ₹5 Lakh, Two Very Different Outcomes
- When Reducing EMI Is Actually the Smarter Call
- When Reducing Tenure Is Almost Always Right
- Prepay the Loan or Invest the Money Instead?
- Home Loan Prepayment Rules and Charges in India
- How to Actually Decide
- The Bottom Line
The Choice That Looks Small But Isn't
Picture two people who each just received a ₹5 lakh bonus and put it toward their identical home loans on the same day. One calls the bank and asks to reduce the EMI. The other asks to reduce the tenure. Five years later, one of them has paid several lakhs less in total interest and owns their home free and clear sooner. The other is still paying a smaller EMI, comfortably, for years longer than necessary. Both made a completely reasonable-sounding choice in the moment. Only one of them actually ran the numbers first.
That's the one thing worth remembering from this entire guide: reducing tenure keeps your EMI the same but shortens how long you pay it, which is almost always the more economical choice, unless your monthly cash flow genuinely needs the relief. The decision isn't about which option feels better this month. It's about whether you actually need lower monthly pressure or whether you're just defaulting to the option that sounds more comforting.
How Home Loan Prepayment Actually Works
A home loan EMI is split into two components every month: a portion that goes toward interest, and a portion that reduces your outstanding principal. Early in the loan, interest dominates the split; principal repayment only starts overtaking it years in. Prepayment, paying an extra lump sum beyond your scheduled EMI, goes directly against the outstanding principal. That's what makes it powerful: it shrinks the base on which all future interest is calculated, for every remaining month of the loan.
Once you make a part-prepayment, the bank offers you two ways to apply the benefit:
- Reduce EMI, keep tenure the same. Your monthly outgo drops, but you continue paying for the originally agreed number of years.
- Reduce tenure, keep EMI the same. Your monthly outgo stays exactly where it is, but the loan finishes sooner, sometimes years sooner.
Both options reduce your total interest compared to doing nothing. The gap between them, in how much interest you actually save, is bigger than most borrowers expect.
The Numbers: Same ₹5 Lakh, Two Very Different Outcomes
Take a ₹50 lakh loan at 8.5% over 20 years, with a ₹5 lakh part-prepayment made after year 3.
| Approach | Monthly EMI | Remaining Tenure | Total Interest Saved |
|---|---|---|---|
| No prepayment (baseline) | ₹43,391 | 17 years remaining | — |
| Reduce EMI option | Drops to ~₹38,900 | Stays at 17 years | Moderate savings |
| Reduce Tenure option | Stays at ₹43,391 | Drops to ~13.5 years | Meaningfully higher savings |
Why the gap exists: when you reduce tenure, every one of those higher EMI payments in the shortened schedule keeps pushing more money against principal, compounding the benefit. When you reduce EMI, you stretch the same lower payment across the original number of years, so the loan keeps accruing interest for longer than it needs to.
These figures are illustrative. Run your own loan amount, rate, and prepayment size through our home loan EMI calculator to see the actual numbers for your situation before you call your bank.
When Reducing EMI Is Actually the Smarter Call
Lower interest savings doesn't mean the wrong choice, in some situations it's the right one. Reducing your EMI makes sense when:
- Your monthly cash flow is genuinely tight, and a lower EMI meaningfully improves your ability to handle other expenses, save, or absorb an income shock.
- You're approaching a life change, a career shift, a child's education costs, a planned career break, where predictable lower outgo matters more than long-term optimisation.
- You want to preserve eligibility for future borrowing, since a lower EMI improves your debt-to-income ratio if you're planning to take another loan soon.
In each of these, you're trading some interest savings for breathing room. That's a legitimate trade, as long as you're making it consciously rather than by default.
When Reducing Tenure Is Almost Always Right
Reducing tenure is the stronger default when:
- Your current EMI is comfortable relative to your income, and losing nothing from your monthly budget by keeping it unchanged.
- You want to be debt-free sooner, particularly as you approach retirement or want the property fully owned before a specific milestone.
- You're prepaying repeatedly over the years, since each tenure reduction compounds the benefit of the last one, accelerating the payoff further each time.
If you're unsure which category you fall into, a rough rule of thumb: if you wouldn't notice the difference in your monthly budget either way, choose tenure reduction. The savings are real money, not just a number on a spreadsheet.
Prepay the Loan or Invest the Money Instead?
Before you prepay at all, it's worth asking whether the money is better used elsewhere. The comparison usually comes down to your home loan interest rate versus your realistic post-tax return elsewhere. If your loan is priced around 8–8.5% and you're confident in earning meaningfully more than that, after tax, over a comparable horizon, investing may edge out prepayment on pure numbers.
But two things weigh in prepayment's favour that a spreadsheet doesn't capture well: prepayment is a guaranteed, risk-free return equal to your loan rate, while market returns aren't guaranteed, and the psychological value of reduced debt and improved sleep is real, even if it doesn't show up in an IRR calculation. If you're debt-averse or the loan is a source of ongoing stress, that's a legitimate factor, not just an emotional one to be talked out of.
Home Loan Prepayment Rules and Charges in India
The rules changed in 2026. Under the RBI's Pre-payment Charges on Loans Directions, 2025, effective from January 1, 2026, banks, NBFCs, and housing finance companies cannot levy any prepayment or foreclosure charges on floating-rate loans taken by individuals for non-business purposes, including home loans, regardless of the amount prepaid or the source of the funds.
Fixed-rate home loans are treated differently: lenders can still charge foreclosure fees at their discretion, provided the charge is clearly disclosed in your loan agreement. If you're on a fixed rate and considering prepayment, check your sanction letter for this clause before assuming it's free.
A few practical rules worth knowing before you prepay:
- Most lenders set a minimum part-prepayment amount, and some restrict how many times a year you can prepay, confirm both with your specific lender.
- You'll need to submit a formal request, in writing or through net banking, specifying whether you want the benefit applied to EMI or tenure. Some lenders default to one or the other unless you specify.
- Ask for a revised amortisation schedule after any prepayment, so you have a written record of exactly how your remaining principal, tenure, and total interest have changed.
How to Actually Decide
Before your next prepayment, run through three questions in order:
- Would a lower EMI genuinely change your monthly financial comfort? If yes, reducing EMI is a legitimate choice. If you wouldn't notice the difference, move to the next question.
- Do you have a specific reason to want the loan closed sooner? Retirement timeline, risk aversion, an upcoming milestone. If yes, tenure reduction directly serves that goal.
- If neither applies strongly, default to tenure reduction. It's the higher-savings option, and you can always request an EMI reduction later if your circumstances change.
The Bottom Line
Prepayment itself is rarely the wrong call, letting it default to whichever option the bank suggests first, usually EMI reduction because it's the easier sell, is where borrowers leave money on the table. The extra five minutes it takes to run both scenarios through a calculator before you submit the request is worth more than almost any other five minutes you'll spend on your loan.
Next time you have a lump sum to put toward your loan, run both scenarios side by side before you call the bank. Which one actually changes your life more, a smaller number on next month's statement, or a shorter distance to owning your home outright?
Tags
Tags
Frequently Asked Questions
Top 5 Best Properties in Delhi NCR This Week
Handpicked properties with best price & location
Popular in Greater Noida
Top-rated residential & commercial projects across Greater Noida